
Frame the decision
Name the audience, requested decision and source pack. Review imported tables and extracted text; record gaps instead of allowing a polished narrative to conceal them.
Generate structured financial analysis briefs with AI. From revenue summaries and cost analysis to investment evaluation and forecasting, organize the evidence, assumptions, and review questions your finance team needs to assess.
An AI financial analysis tool is software that organizes a financial-analysis brief from the source material you provide. Gixo's workflow checks extracted figures against uploaded documents, adds citations where the source supports them, and leaves the finance team to verify calculations, assumptions, forecasts, and proprietary data. It is a document-synthesis aid for directional analysis, not a spreadsheet engine, accounting system, valuation model, or substitute for finance review.
Variance analysis compares an actual result with an explicit baseline for the same period, measure and unit. In a fictional worked example, actual cost of 120 against a budget of 100 produces a cost variance of +20, or +20% of budget.
| Part | Worked detail |
|---|---|
| Absolute variance | Actual − baseline = 120 − 100 = +20. |
| Percentage variance | (Actual − baseline) ÷ baseline × 100 = 20% when the baseline is 100. |
| Meaning | For cost, a positive variance may be unfavorable; for revenue it may be favorable. State the convention. |
| Zero baseline | A zero baseline has no ordinary percentage variance. Report the absolute change and explain the basis instead. |
Separate the calculation from the explanation. Analyst can support reviewable tables and calculation evidence inside Business, while the narrative records assumptions, source gaps and decisions. Replayable arithmetic does not independently validate supplied figures or establish the cause of a change.
A worked workflow
A fictional operating table reports a GBP 100,000 quarterly cost budget and GBP 120,000 actual cost. A related note says staffing was higher, but supplies no evidence that staffing caused the whole variance.
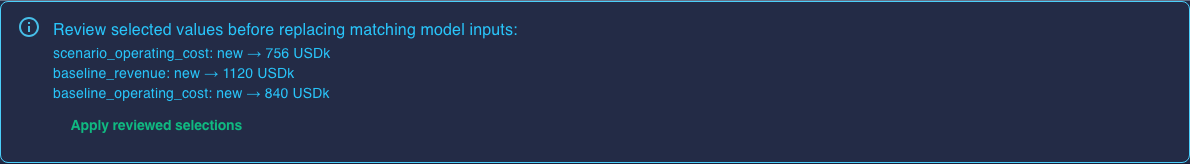
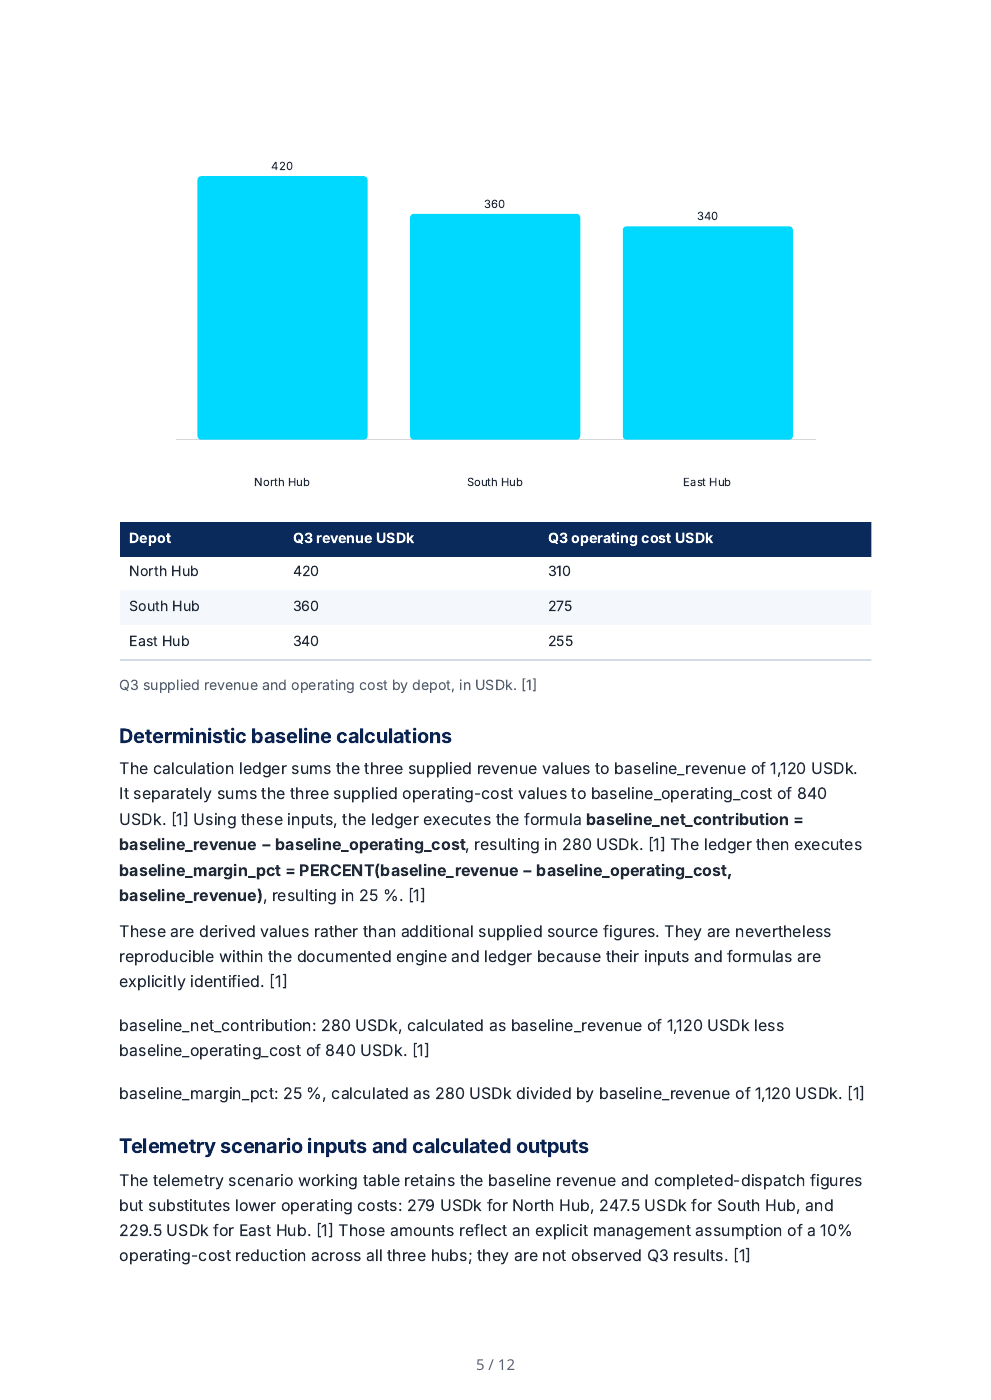
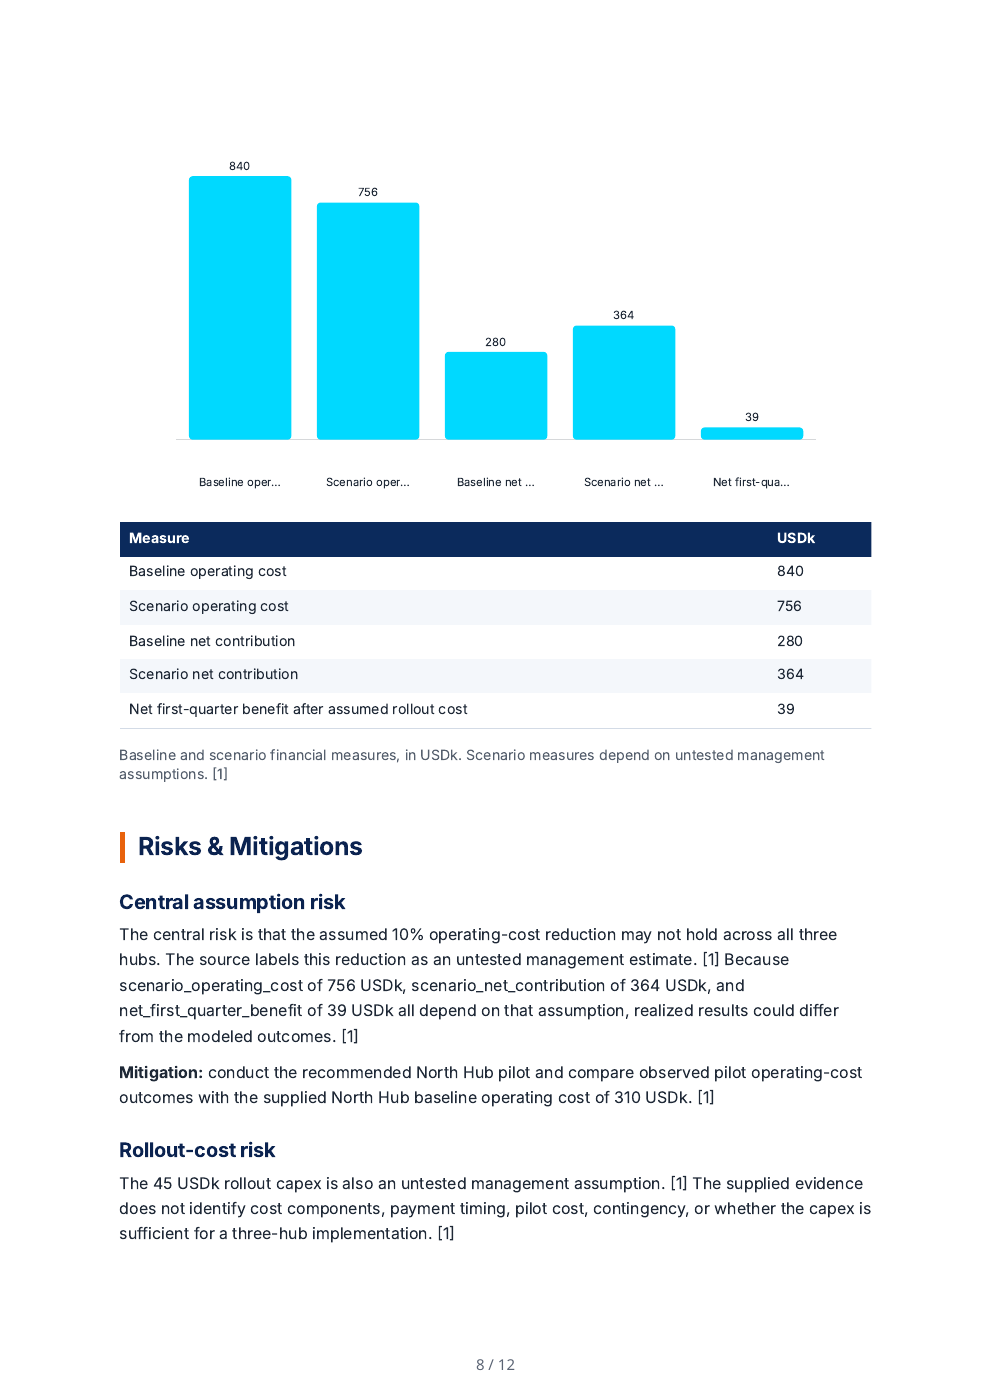
The supplied fictional depot table totals USD 1,120k revenue and 840k operating cost. A manually entered 10% cost-reduction scenario totals 756k cost. Reviewed selections feed the model; the replay computes baseline contribution 280k, baseline margin 25%, scenario contribution 364k and first-quarter benefit 39k after an assumed 45k rollout cost. The generated report keeps those assumptions distinct from supplied figures.
A passed calculation replay checks arithmetic for the supplied definition; it does not validate the source figures or establish that a 10% reduction will occur. Working-table XLSX import/export stores typed literal values; define formulas in the calculation model. This operational dossier is not a board-approved result.
Inspect extracted rows, headers, units, period and source location. Resolve conflicting totals or keep the conflict visible.
Inspect: A calculation over a mismatched period or a thousands-versus-units error can be mechanically correct and still answer the wrong question.
Map the approved actual and baseline values, inspect the computation and retain calculation evidence.
Inspect: For cost, +20% is an overrun in this convention. For a revenue measure, the same arithmetic may have a different business interpretation.
Compare component movements and any supported explanation before drafting the narrative.
Inspect: Do not turn a note mentioning staffing into proof that staffing explains all GBP 20,000. Retain the unsupported portion as an open question.
Open the calculation/workbook handoff and the resulting report paragraph separately. Review scenario assumptions before selecting a scenario.
Inspect: Changing a numeric input should affect the computed result; it does not automatically approve a new narrative or establish the input’s accuracy.
Fictional financial inputs and arithmetic illustration. Business provides decision support; replayable calculation does not constitute audit assurance, source verification or investment advice.
Business · inspectable review specimen
A decision memo should connect the chosen source definition to reproducible arithmetic, then state the decision and its limits. A larger number from another source is not automatically the right numerator.
Authored fictional instructional sample. The downloadable Word file is rendered through Gixo’s real document exporter. This is separate from the captured product workflows on this page.
All figures below are fictional supplied data for April 2026, in USD thousands. Finance source F-01 reports recognized revenue of 1,120 and operating cost of 840. Sales source S-01 reports signed bookings of 1,180. These are different measures, not two interchangeable revenue estimates.
| Measure | Value | Disposition |
|---|---|---|
| Recognized revenue (F-01) | 1,120 | Use for this operating-margin calculation |
| Signed bookings (S-01) | 1,180 | Keep separate; do not substitute for recognized revenue |
| Operating cost (F-01) | 840 | Same period and units |
| Operating contribution | 280 | 1,120 − 840 |
| Contribution margin | 25% | 280 ÷ 1,120 × 100 |
Authorize a limited cost review before changing the operating plan. This specimen proposes a review; it does not record board approval or an observed business outcome.
If cost rises by 5% while recognized revenue stays unchanged, scenario cost is 882, contribution is 238 and margin is 21.25%. This is an assumed scenario, not a forecast. The finance reviewer should confirm recognition policy, completeness and period alignment before a real decision.
Record the source revision, mapping decision, calculation, responsible reviewer and next review date. Keep the unresolved explanation for cost changes visible instead of assigning a cause without evidence.
Authored decision-memo specimen with reproducible supplied arithmetic. The separate captured Analyst working tables remain product evidence; this is not a new live Business analysis run.
Inspect an actual Business report. A readable decision brief needs the question, supplied evidence, options, assumptions and next decision—not just a shorter source document.
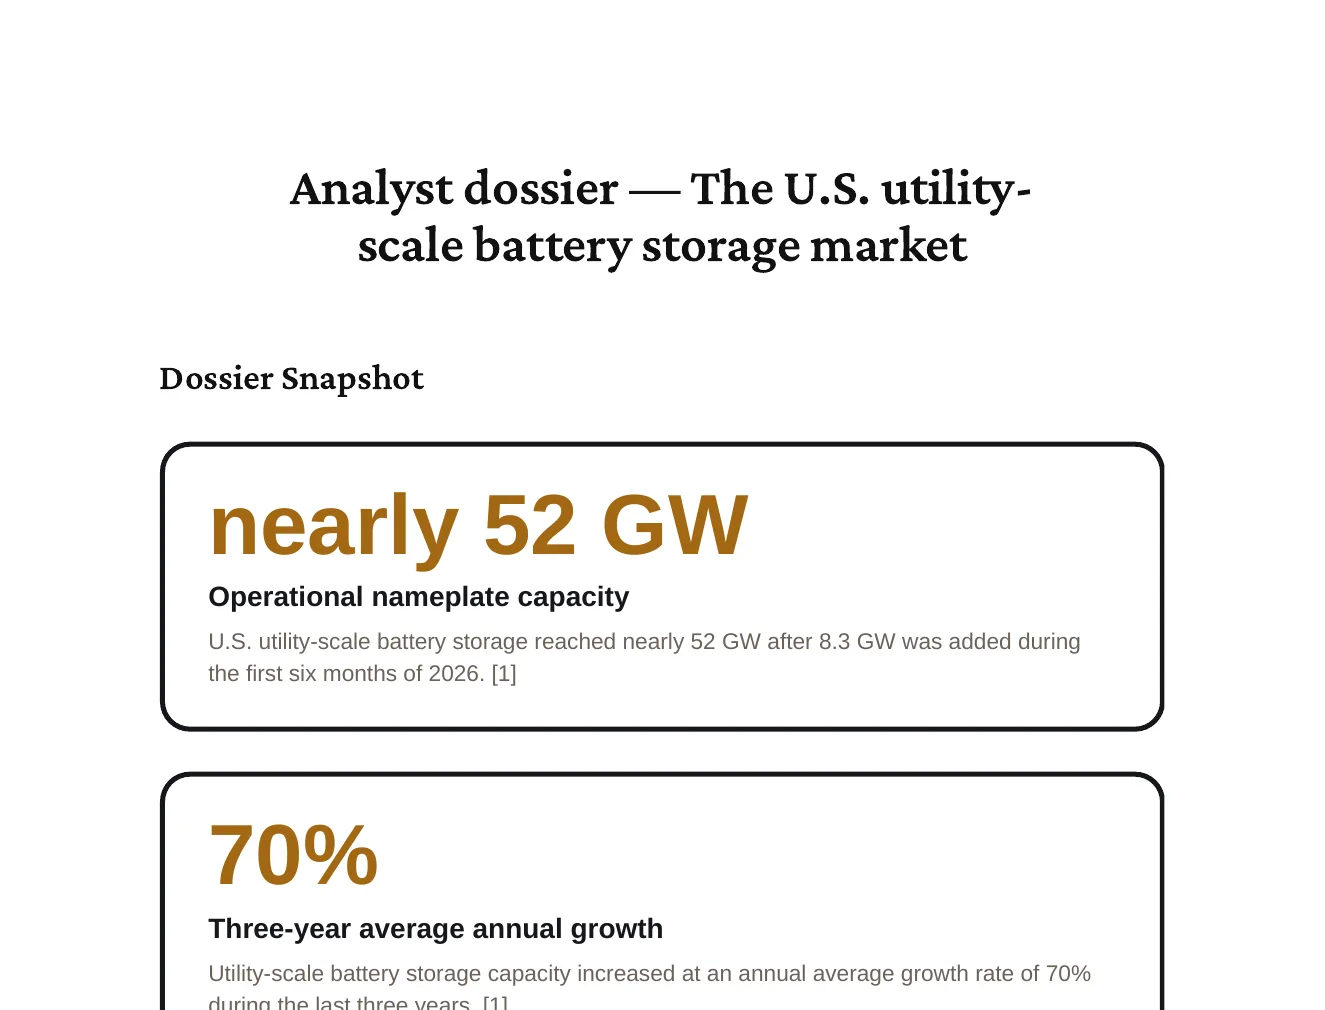
A dossier built from four public EIA pages: a snapshot of figures, an executive summary, market size and growth, key drivers and trends, the competitive landscape, segments and buyers, an outlook, recommendations and a sources appendix, ending with the product's own faithfulness review of the text.
Research target: The U.S. utility-scale battery storage market. Focus: How fast U.S. utility-scale battery storage capacity has grown, what is planned for 2025 and 2026, and how battery storage compares with the other kinds of generating capacity being added. Describe a trend, ranking or comparison only where a source states it, and say where the sources are silent.
Open the full export and compare its statements with the cited sources before reuse.
Name the audience, requested decision and source pack. Review imported tables and extracted text; record gaps instead of allowing a polished narrative to conceal them.
Separate supplied facts, calculated values, assumptions and recommendations. For variance work, reconcile the period, unit, baseline and actual value before interpreting the direction of a difference.
Use options, trade-offs, risks and named next actions. Review the final artifact and, when using Analyst calculations, inspect the calculation evidence separately from the narrative.
Select source documents, case context, working notes, assumptions, options and decision constraints before generation. Inspect claims, metrics, exact quotations, source tables and conflicting figures. Review decisions are scoped to the source or artifact and can become stale after evidence changes; unresolved evidence should stay visible.
Keep investment, recurring costs, benefits, delays, growth, discount assumptions and scenario probabilities explicit. Inspect deterministic cash flow and the available return, payback and sensitivity outputs. Compare scenarios before selection, and inspect the formula workbook or calculation receipt separately from the narrative recommendation.
Inspect the dossier's source tables, working rows and columns, calculation ledger and workbook handoff. Metric packs retain reviewable calculation and source context. Preview source replacements for a new period before accepting them. Execution records distinguish an action owner, baseline, target, measured value, data source and the reason for a status change.
A calculation can be replayable while the supplied inputs remain wrong. A generated report is decision support, not independent diligence, audit assurance or investment advice.
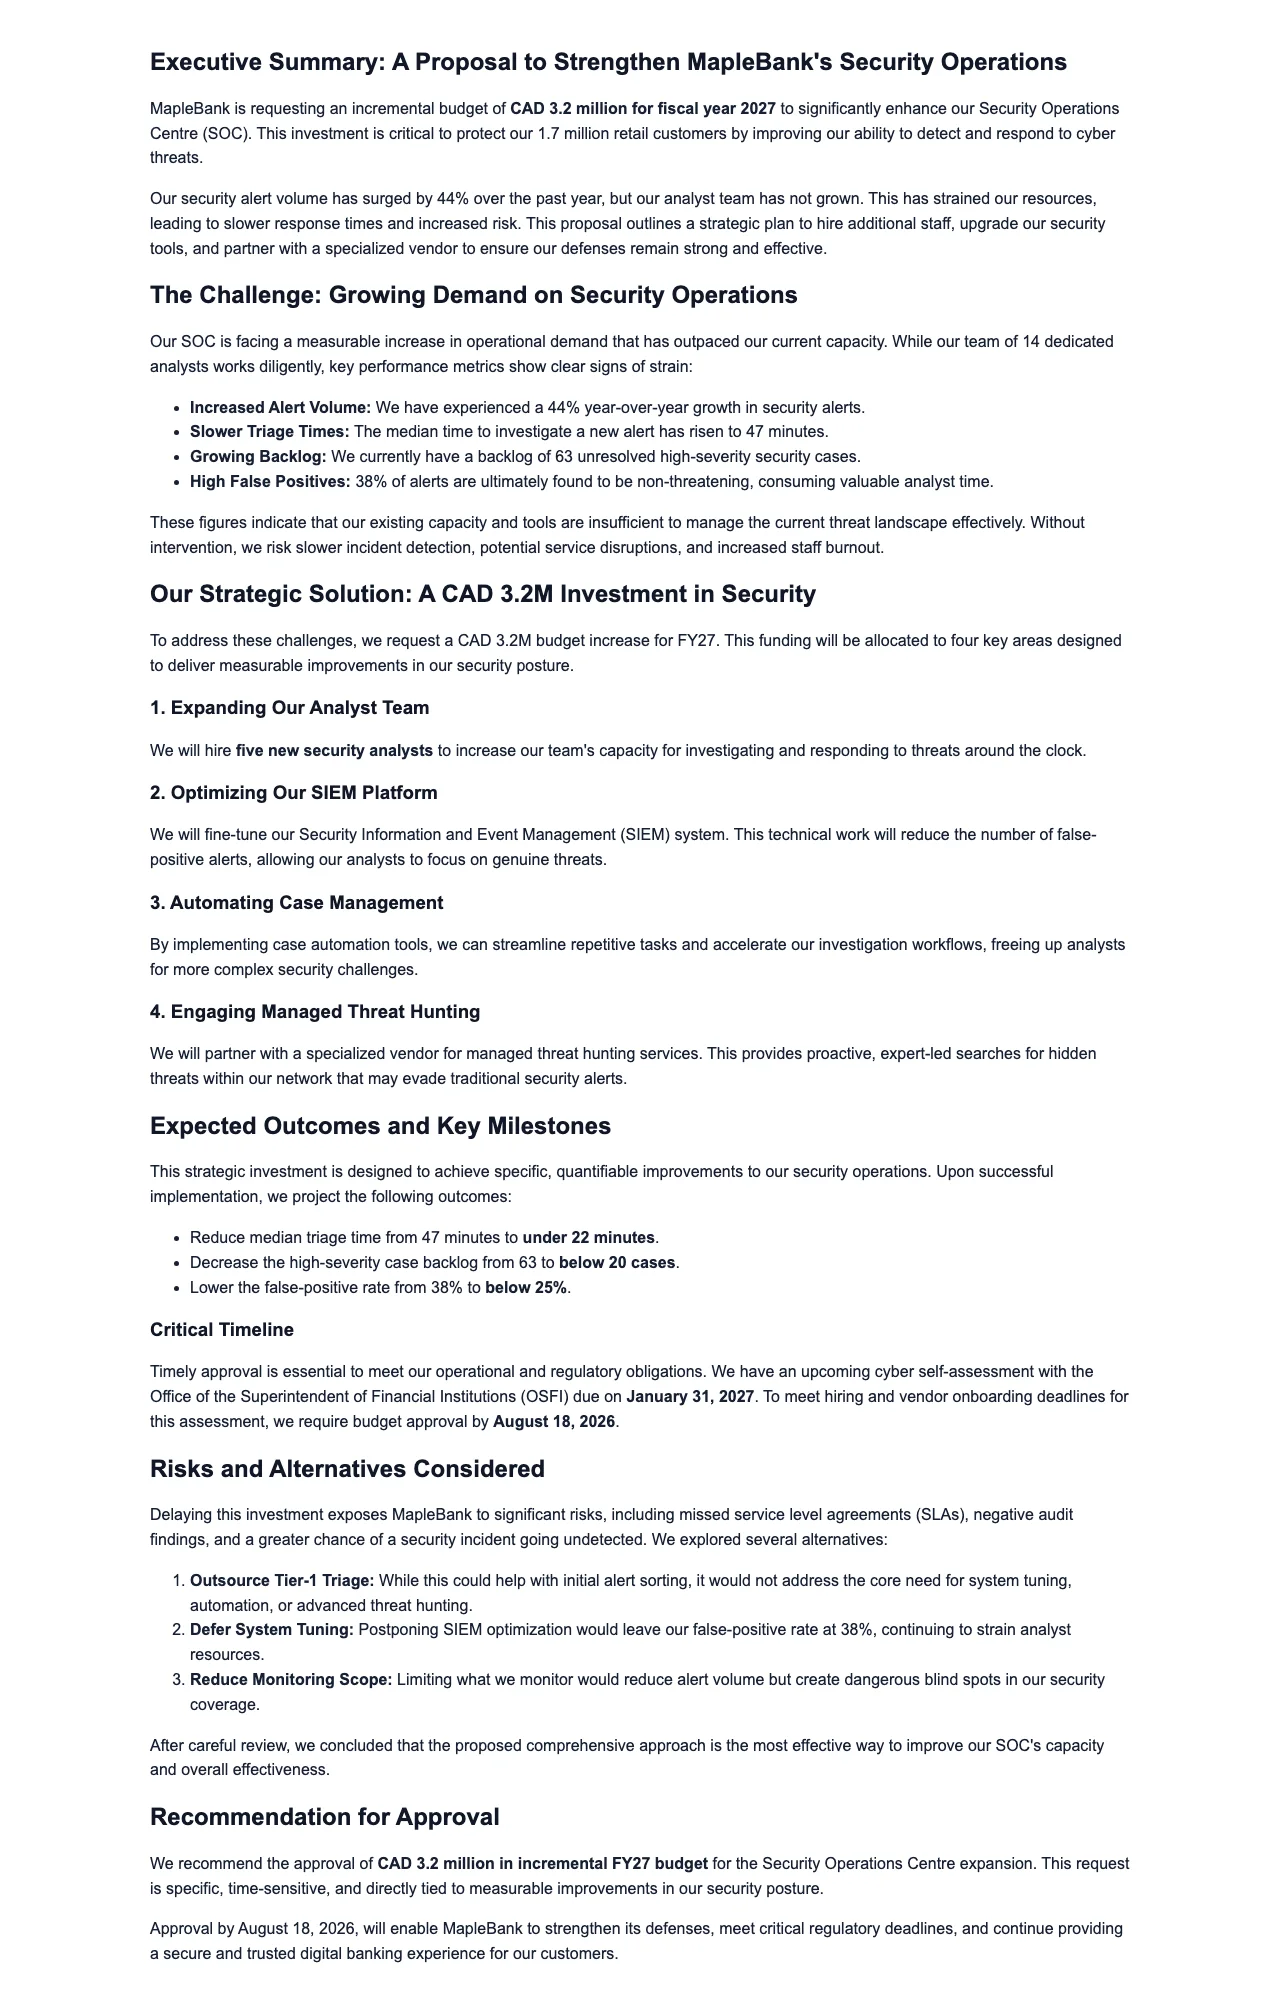
Get structured financial analysis that would take your team days to compile — covering revenue, costs, investments, and forecasts.
Analyze supplied revenue streams, growth assumptions, pricing context and monetization options in a draft financial brief. Business attempts to reconcile figures with source material; failed repairs can retain original values. Finance must check the calculation, period, denominator and underlying assumptions before using the analysis.
Identify cost reduction opportunities and resource allocation improvements using Pros/Cons blocks for trade-off analysis. The number-reconciliation stage can compare stated savings with the source text you uploaded. Finance still validates the savings model, timing and assumptions.
Organize investment options and supplied ROI assumptions in editable comparison sections. Numbered uploaded-file markers can help locate evidence, but the model can omit them or associate them with an unsupported interpretation. Have Finance validate the source figures and investment calculations before committee review.
Structure financial projections with KPI blocks for key metrics and Steps blocks for scenario assumptions. Use Quick AI for instant rewrites or Power Edit for full AI dialog to refine projections as new data becomes available.
Supply the dated peer data and benchmark definitions you want compared. Use KPI blocks to present the reviewed figures, and check citation markers against the original files. Business does not provide a licensed benchmark database or validate that the selected peers are comparable.
Every financial brief runs through a multi-stage pipeline with brand compliance before structural validation, and a brief written from uploaded sources also gets number checks and citations against them. The result is a draft for finance review. Check that the summary and recommendation match the reviewed evidence and calculations.
Enter the financial topic — revenue analysis, cost structure evaluation, investment opportunity, market valuation, or financial health assessment.
Choose the analysis focus — industry benchmarking, competitive financial comparison, trend analysis, scenario modeling, or comprehensive financial review.
Business generates a financial-analysis draft from the reviewed outline and supplied material, with supported terminology and structure checks. It attempts source-based number reconciliation and requests citation markers; neither guarantees corrected figures or complete citation coverage. Inspect generated-draft Evidence findings, source passages and the underlying model before use.
Edit with 20+ semantic blocks including KPIs and Comparison Tables. Use Quick AI for instant rewrites or Power Edit for deeper revisions. On Business Professional or higher, authorized finance colleagues can comment on and review the saved brief. Resolve save conflicts, confirm the figures and export the reviewed version.
Business organizes the narrative around the figures; it does not replace the workbook that calculates them.
Compare a source-grounded financial brief with the calculation and review work that remains in a spreadsheet and finance process.
| Evaluation area | Gixo Business | What to check in finance-team and advisory workflows |
|---|---|---|
| Job and inputs | Organize supplied financial figures and assumptions; validate the workbook, benchmark and forecast separately. | Test the current product or scoped service against the same question, sources and deliverable. |
| Evidence review | Inspect source coverage, uploaded-file citation markers and generated-draft Evidence and citation findings. | Check source support and current research capabilities; a citation alone does not confirm the conclusion. |
| Revision and delivery | Edit the brief, retain saved versions and review the final export. | Test the actual review, collaboration, version and export workflow you need. |
| Timing and responsibility | Generation time varies with the job and source pack; accountable people review the result. | Compare the agreed scope and review responsibilities rather than assume fixed speed or price. |
For a brief written from sources you upload or from the search results web research drew on, the Evidence tab under Checks in the brief editor lists up to five sentences or table cells whose wording or figures it could not match to those sources, for you to check. It matches wording and exact figures, not meaning: a faithful paraphrase, or $8.1M where the source says 8,100,000, can fail to match while being true, so an unmatched sentence is a place to look, not an error, and a matched one is not confirmed either, because this is a comparison with your own sources, not a fact-check. It reads only part of a long source (24 passages of up to 1,600 characters) and at most 12 sources, files first. Of web research it reads the title and snippet of each search result, not the page, so a figure taken from the page alone does not match, and if it could not read every result the list is advisory. It reads a table cell with its row and column, and a total the table works out from its own cells passes when the arithmetic holds. It checks the draft as generated, not your later edits.
A business case financial model connects the stated assumptions to the figures a finance reviewer can inspect. A financial brief explains the case. In a formal Business Case, enter initial investment, one-time costs, monthly operating cost and benefit, the start delay, discount rate and annual growth assumptions. Compare up to 5 named scenarios over a horizon of one to 240 months. Keep the reporting period, currency and evidence behind each input visible for the finance reviewer.
The case calculates monthly cash flows, NPV, ROI, payback and whether break-even is achieved within the horizon, with a three-by-three sensitivity view of benefit and cost changes. Probability-weighted expected NPV is available only when every scenario has a probability and the total is 100 percent. These probabilities are entered assumptions. The current case model does not calculate IRR or run a Monte Carlo simulation; include an external model result only with its inputs and a reviewer who can check it.
Saving the case recalculates the scenario inputs on the server. A governed approved-case memo checks the approved revision snapshot and reconciles supported calculation results before export. Figures entered manually are labelled author-attested rather than recomputed. Snapshot capture or PDF rendering can be unavailable, so approval alone does not guarantee a downloadable memo. Review the assumptions and source meaning as well as the arithmetic.
Review Business Case governance and export boundaries · Follow the financial-case controls in the Business guide
Use this variance analysis software workflow to calculate the gap between planned and actual values from reviewed inputs. In Business Analyst, inspect the supplied spreadsheet or CSV table, then map reviewed cells or aggregates to named calculation inputs. Confirm the labels, period, units and planned-versus-actual basis before applying the mapping. Working tables can be edited, but a changed table or model can make an earlier projection stale and require another review.
Define the arithmetic in the bounded decimal calculation workbook and replay it from the selected inputs. For example, a fictional monthly cost plan of $12,000 and an actual cost of $13,200 produce a $1,200 adverse cost variance, or 10 percent of plan. A zero plan needs an explicit reporting rule instead of an invented percentage. The calculation does not explain the cause of the variance; the author supplies that interpretation and checks the underlying records.
For the next reporting period, reuse the saved review recipe, compare changed source cells and confirm changed mappings before recording the replayed review. The current workbook and review receipt can be downloaded. This is an explicit review workflow, not an automatic ERP or accounting reconciliation feed. Analyst uses supported expressions and stored source-cell values; it does not execute imported Excel formulas, macros or external links, and exported result sheets are snapshots.
Explore Analyst source tables and calculations · See the mapping, replay and repeated-review steps
Actual controls captured on 10 October 2026 with fictional, manually supplied material. These examples show planning, review and editing actions, plus deterministic calculations. Each caption states what was completed. Paid controls require current Business access and the appropriate content role.
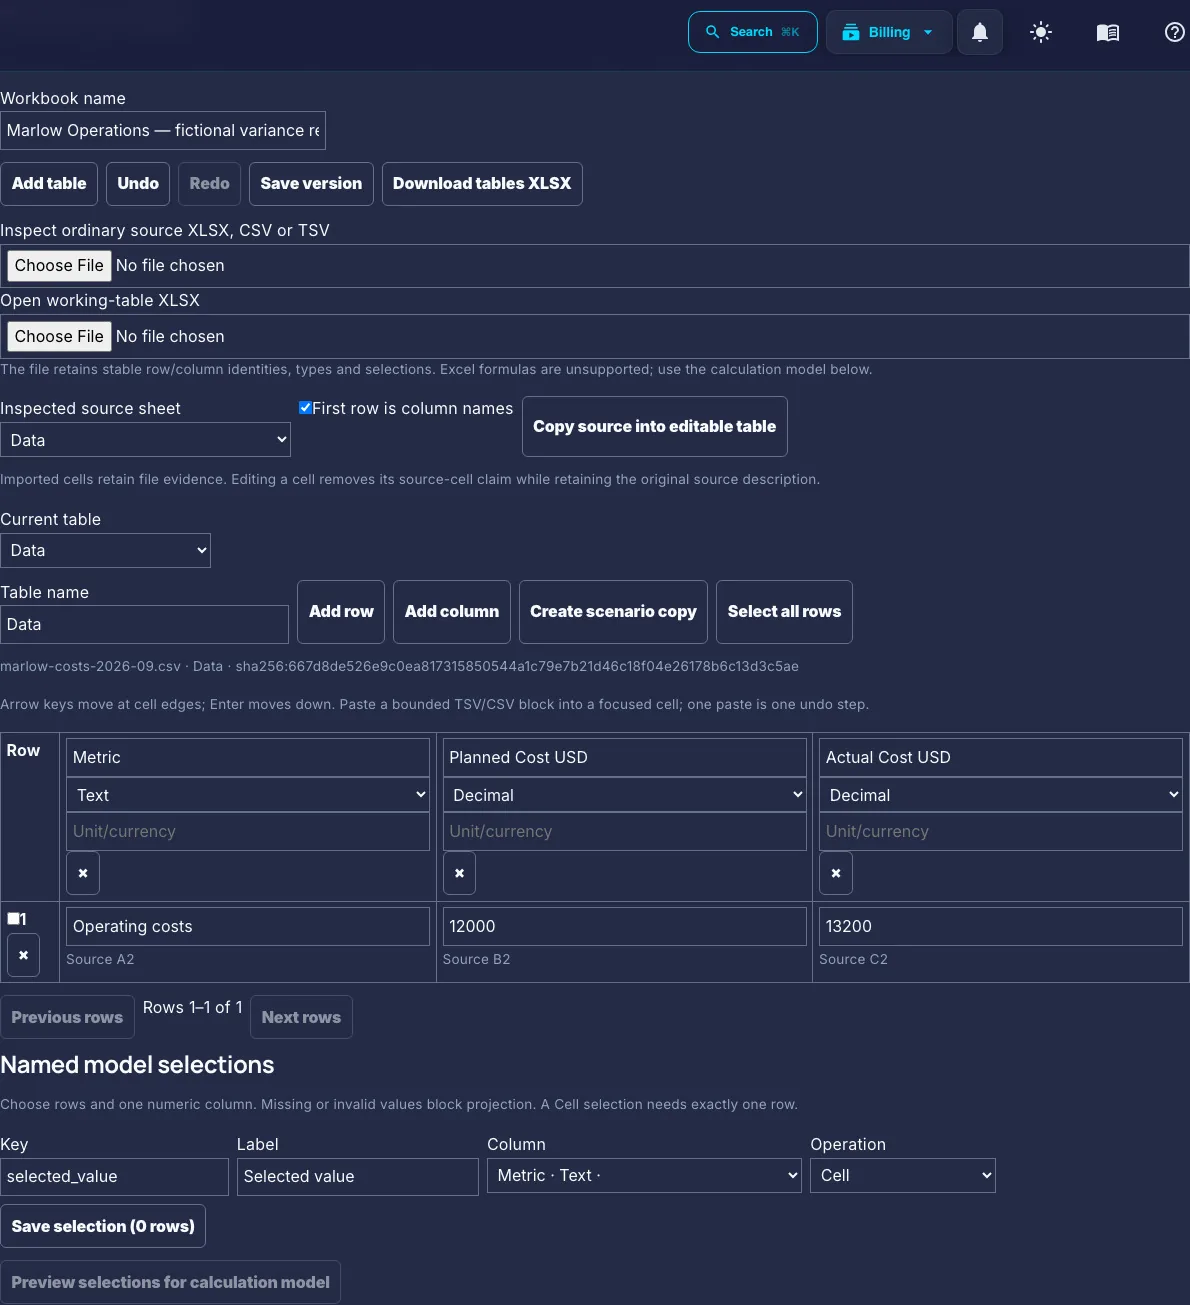
An actual fictional CSV is copied into the Analyst working table. Saved source-cell values are visible; imported Excel formulas are not executed.
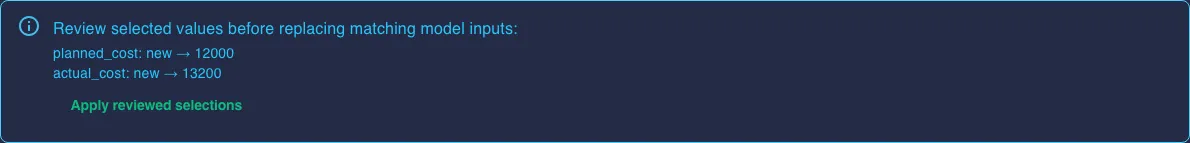
The real projection shows planned_cost = 12000 and actual_cost = 13200 before applying the reviewed selections. Supplied figures are not independently verified.
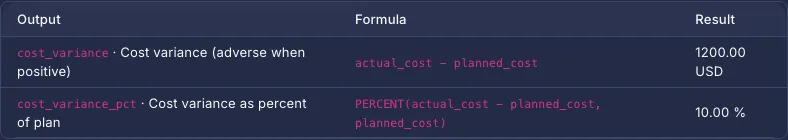
Actual deterministic results: 13200 minus 12000 is 1200 USD adverse variance, or 10% of plan. The workbook was saved; no narrative dossier was generated.
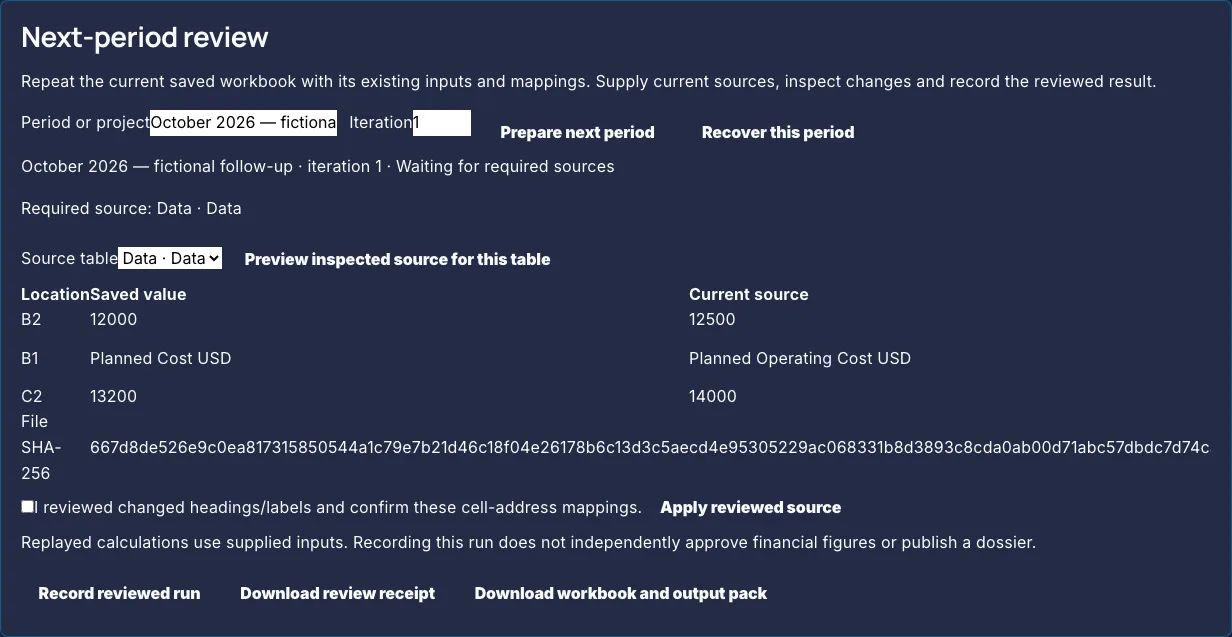
New fictional values 12500/14000 and a changed heading appear beside saved values. The mapping checkbox was later confirmed; changes were not applied and no period review was accepted.
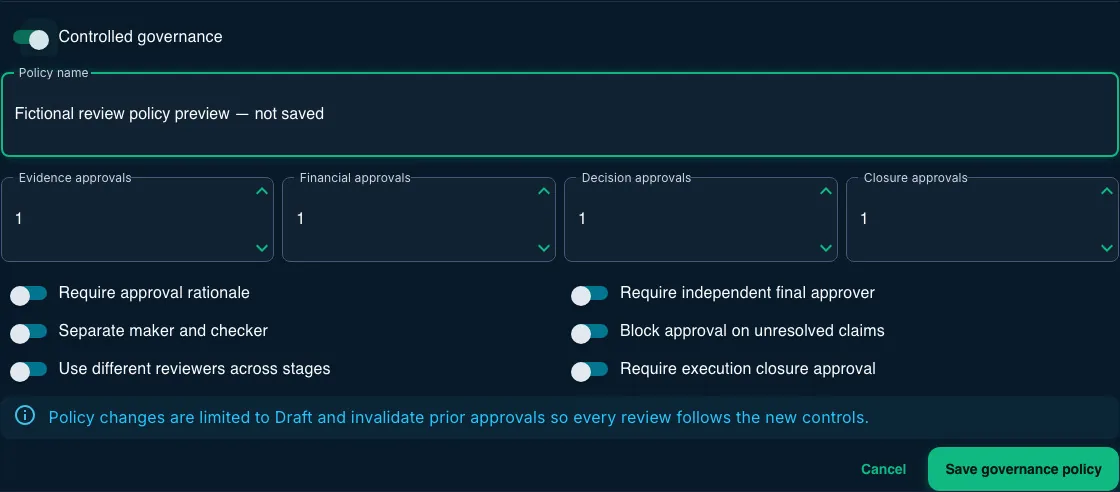
Real Draft policy controls with approval counts and reviewer-separation options. This policy preview was canceled; the case remains unapproved.
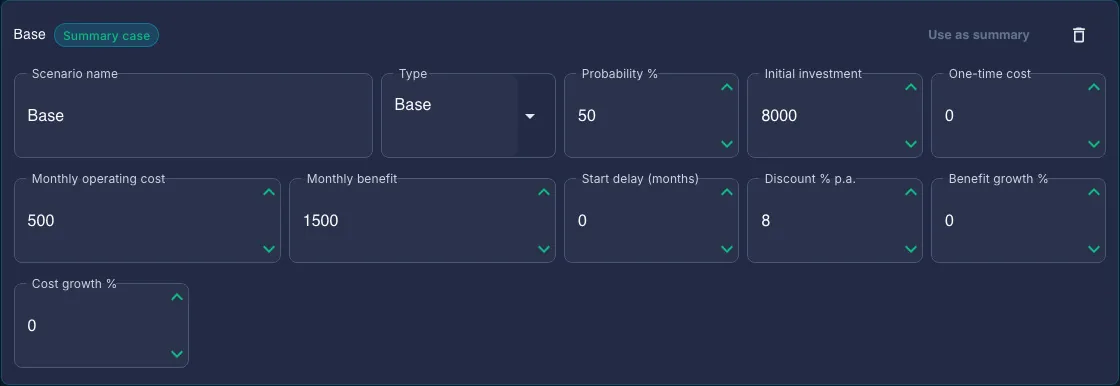
The fictional Base scenario uses 8000 initial investment, 500 monthly cost and 1500 monthly benefit. These are author assumptions, not measured savings.
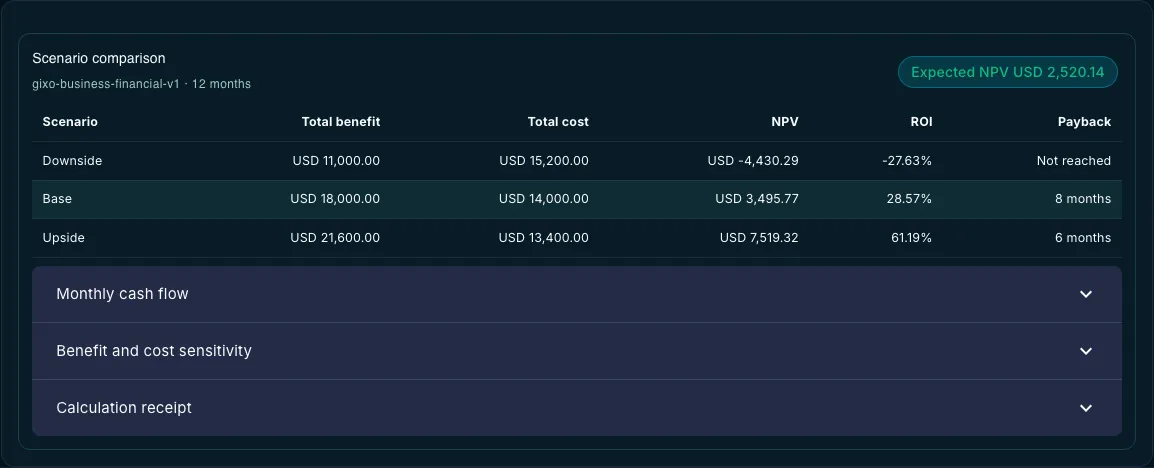
Server-saved fictional Draft case: Base NPV 3495.77 USD, ROI 28.57%, payback 8 months. Expected NPV 2520.14 uses entered 25/50/25 probabilities. Approval and governed memo export were not completed.
Follow the complete Business guide · Understand the source and approval boundaries
Updated